


 19 / 160

17
Hyprop Investments Limited
Integrated annual report 2016
Developments
We continued to enhance our existing portfolio, spending R178 million
during the period on capital projects, replacing equipment and
tenant installations. Included in our equipment spend was the cost
of upgrading security systems at all our malls, installing additional
generators at some malls, and installing smart-metering systems across
our retail portfolio.
Completed projects are summarised below, while extensions are
planned for Canal Walk and Rosebank Mall at an estimated project
cost of R167 million. Key projects during the year included:
Extensions and developments completed
Somerset Mall
Woolworths extension, food court
upgrade, tenant relocations
Clearwater Mall
H&M extension
Under construction
Somerset Mall
Extension to accommodate a large H&M
store – opening October 2016
Atterbury Value Mart Checkers – opening November 2016
Customer security at our shopping centres remains a priority and,
in line with our security strategy, we have installed up-to-date
technology with improved results.
There are a number of masterplan expansion opportunities at some
of our shopping centres, although implementation depends on
planning approvals by local councils and the commitment of key
tenants.
Sub-Saharan Africa
Our sub-Saharan Africa portfolio excludes South Africa. The
review period was characterised by lower economic growth in
Ghana, Zambia and Nigeria – our principal operating territories –
accompanied by weakening local currencies.
Sep
2013
Jun
2016
Mar
Dec
Jun
2015
Mar
Sep
Dec
Sep
Jun
2014
Mar
Dec
■
Ghana
■
Nigeria
■
Zambia
■
South Africa
Exchange rate volatility
0,0
0,5
1,0
1,5
2,0
2,5
Trading density growth slowed during the period, primarily reflecting
the impact of increased competition for The Glen. Excluding this
centre, trading density growth for the rest of the portfolio was 6,4%.
Similarly, excluding The Glen from the rent ratio leaves it unchanged
year-on-year at 7,1%. The Glen remains a popular centre, and the
impact of new competition is already subsiding. Initiatives are under
way to stabilise trading densities and return The Glen to growth.
Leasing
Contractual lease escalations, the basis of growth in annual
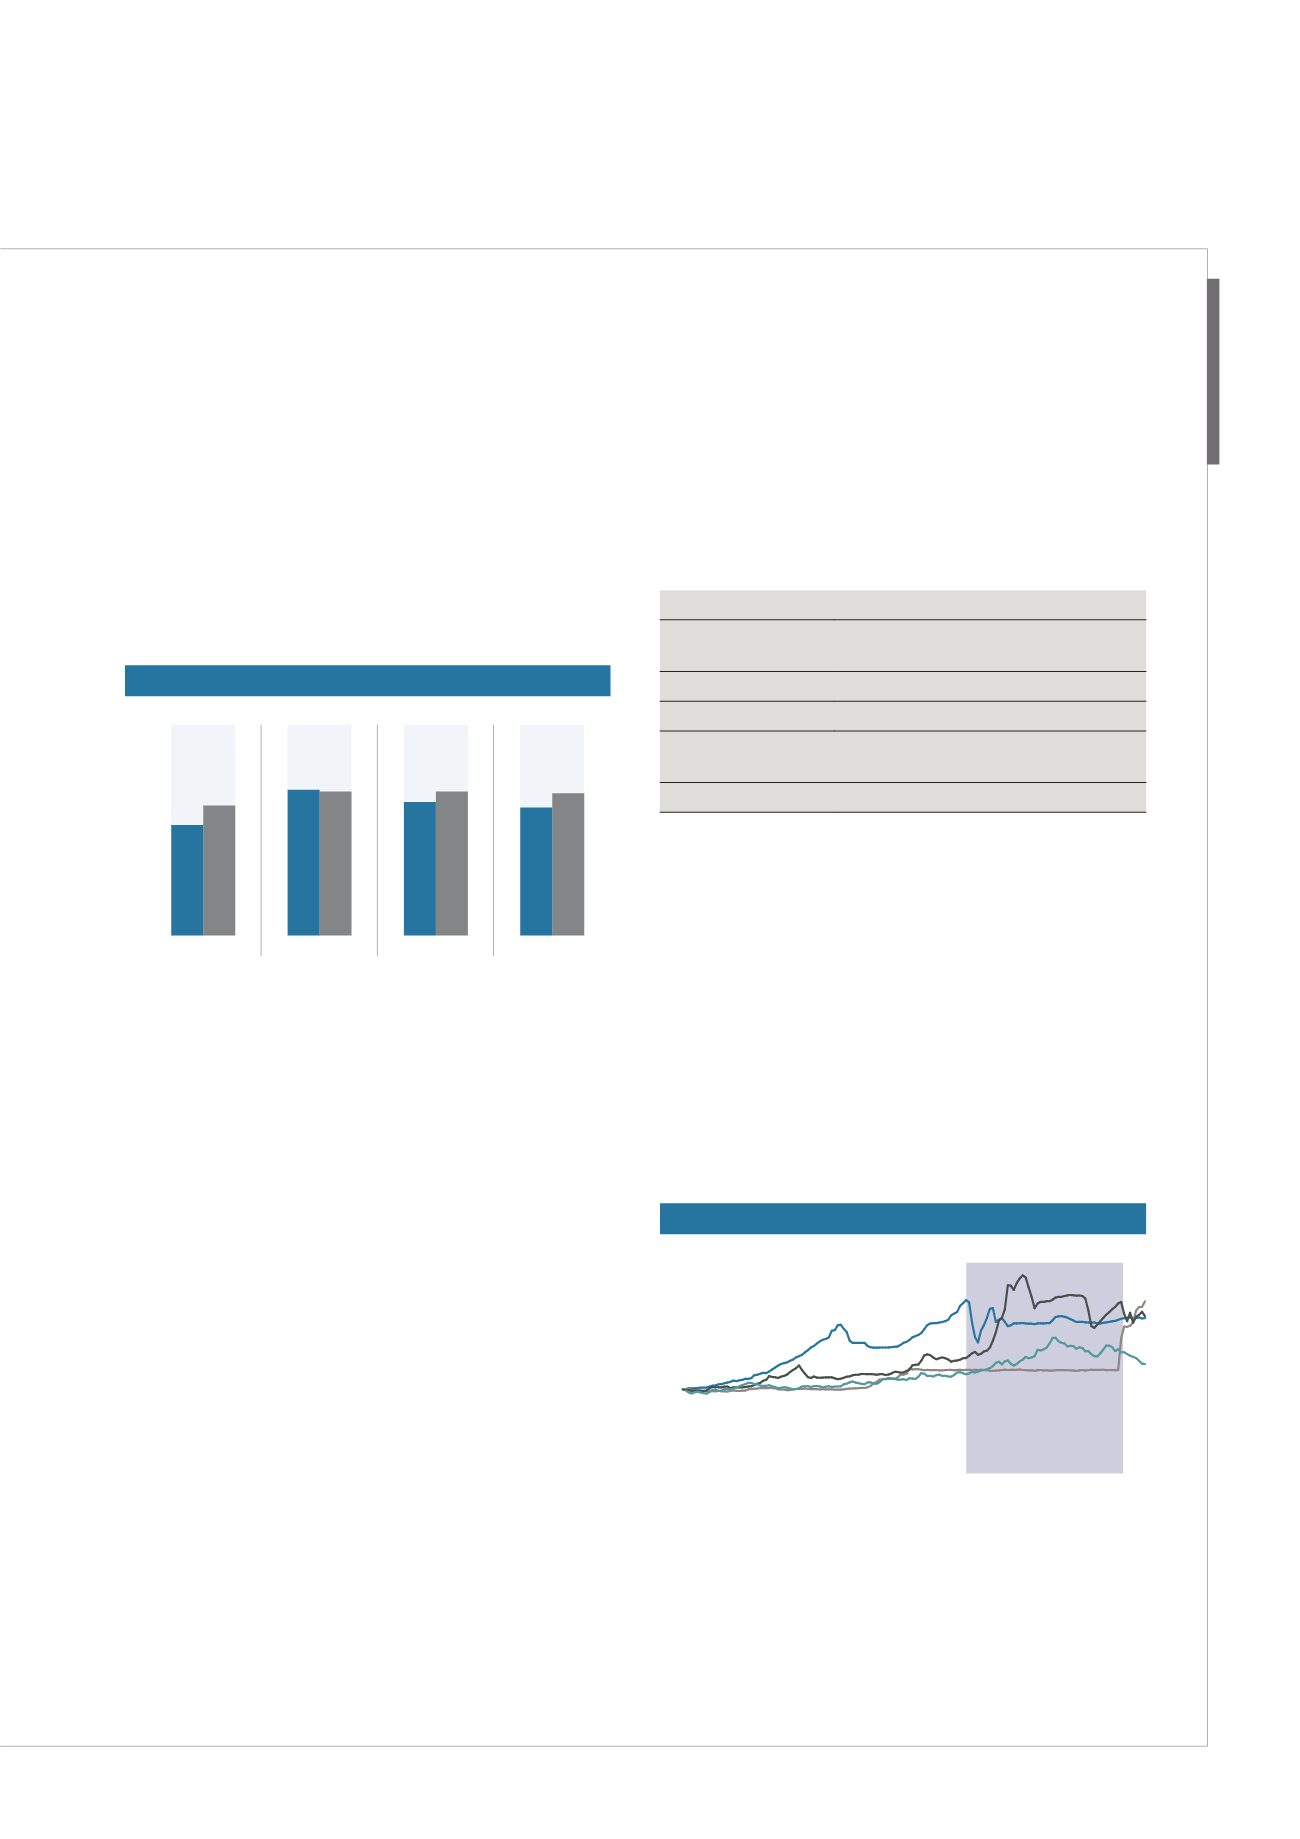
distributable income, dipped marginally to 8,1%. Rental growth on new
leases and renewals slowed to 7,3%, primarily reflecting weak demand
for space in our office portfolio, although vacancies improved to 4,5%
from 8,3% in 2015.
0
2
4
6
8
10
12
7,3% 8,1%
2016
7,6% 8,2%
2015
8,3% 8,2%
2014
6,3% 7,4%
2013
■
Rental growth
■
Contractual escalation
Leasing terms
It was another busy period, with 568 leases signed in South Africa,
representing 153 664m
2
(19,6% of our total portfolio by rentable
area). Our focus remains on continuously improving the tenant mix
by replacing weaker tenants with much stronger and sought-after
retailers. We again accommodated the aims of local national tenants,
for example Woolworths, to expand their store sizes, and capitalised
on demand from international brands establishing a presence in South
Africa. Notably, the first Starbucks outlet in South Africa opened
in Rosebank in April 2016 and the first H&M in Hyprop’s portfolio
opened at Clearwater Mall in the same month.
Edcon
We continue to monitor the financial stability of the Edcon Group.
This remains a risk, as Edcon is the largest tenant group in our
portfolio, occupying 9% of our portfolio by rentable area and
contributing almost 7% of our income. Edcon’s issues relate mainly
to high debt and its ability to provide credit to customers. During
the year, Edcon restructured its debt to improve its financial position
and strengthen its balance sheet. Analysed by trading density and
profitability, most Edcon stores in our portfolio range from average
to good, and we have appropriate contingency plans in place.
Platinum Group
Platinum Group stores were vacated and the space was relet.