


 18 / 160

Hyprop Investments Limited
Integrated annual report 2016
16
CHIEF EXECUTIVE OFFICER’S REPORT
The proven quality of Hyprop’s specialist shopping centre portfolio underpinned
consistent growth for the 12 months to 30 June 2016. At the interim stage, we
raised our guidance to the market to expect distribution growth of 13% to 15%
for the year, and we delivered 14,2%.
Operational performance
A number of factors contributed to the growth in distributable earnings,
including almost 9% growth in distributions from our South African
portfolio, additional income from acquisitions in Nigeria, Montenegro
and Serbia and the opening of Achimota Retail Centre in Ghana.
South Africa
Demand for retail space remained strong with vacancies in the
domestic portfolio reducing to 0,8% from 1,3% a year ago, after new
lettings at Somerset Mall, Willowbridge and Somerset Value Mart in
our retail portfolio, and at Lakefield Office Park and Hyde Park offices.
Post year-end, in line with our strategy of disposing of non-core
assets, we concluded sale agreements for Somerset Value Mart and
Glenfield Office Park for R185 million and R180 million, respectively.
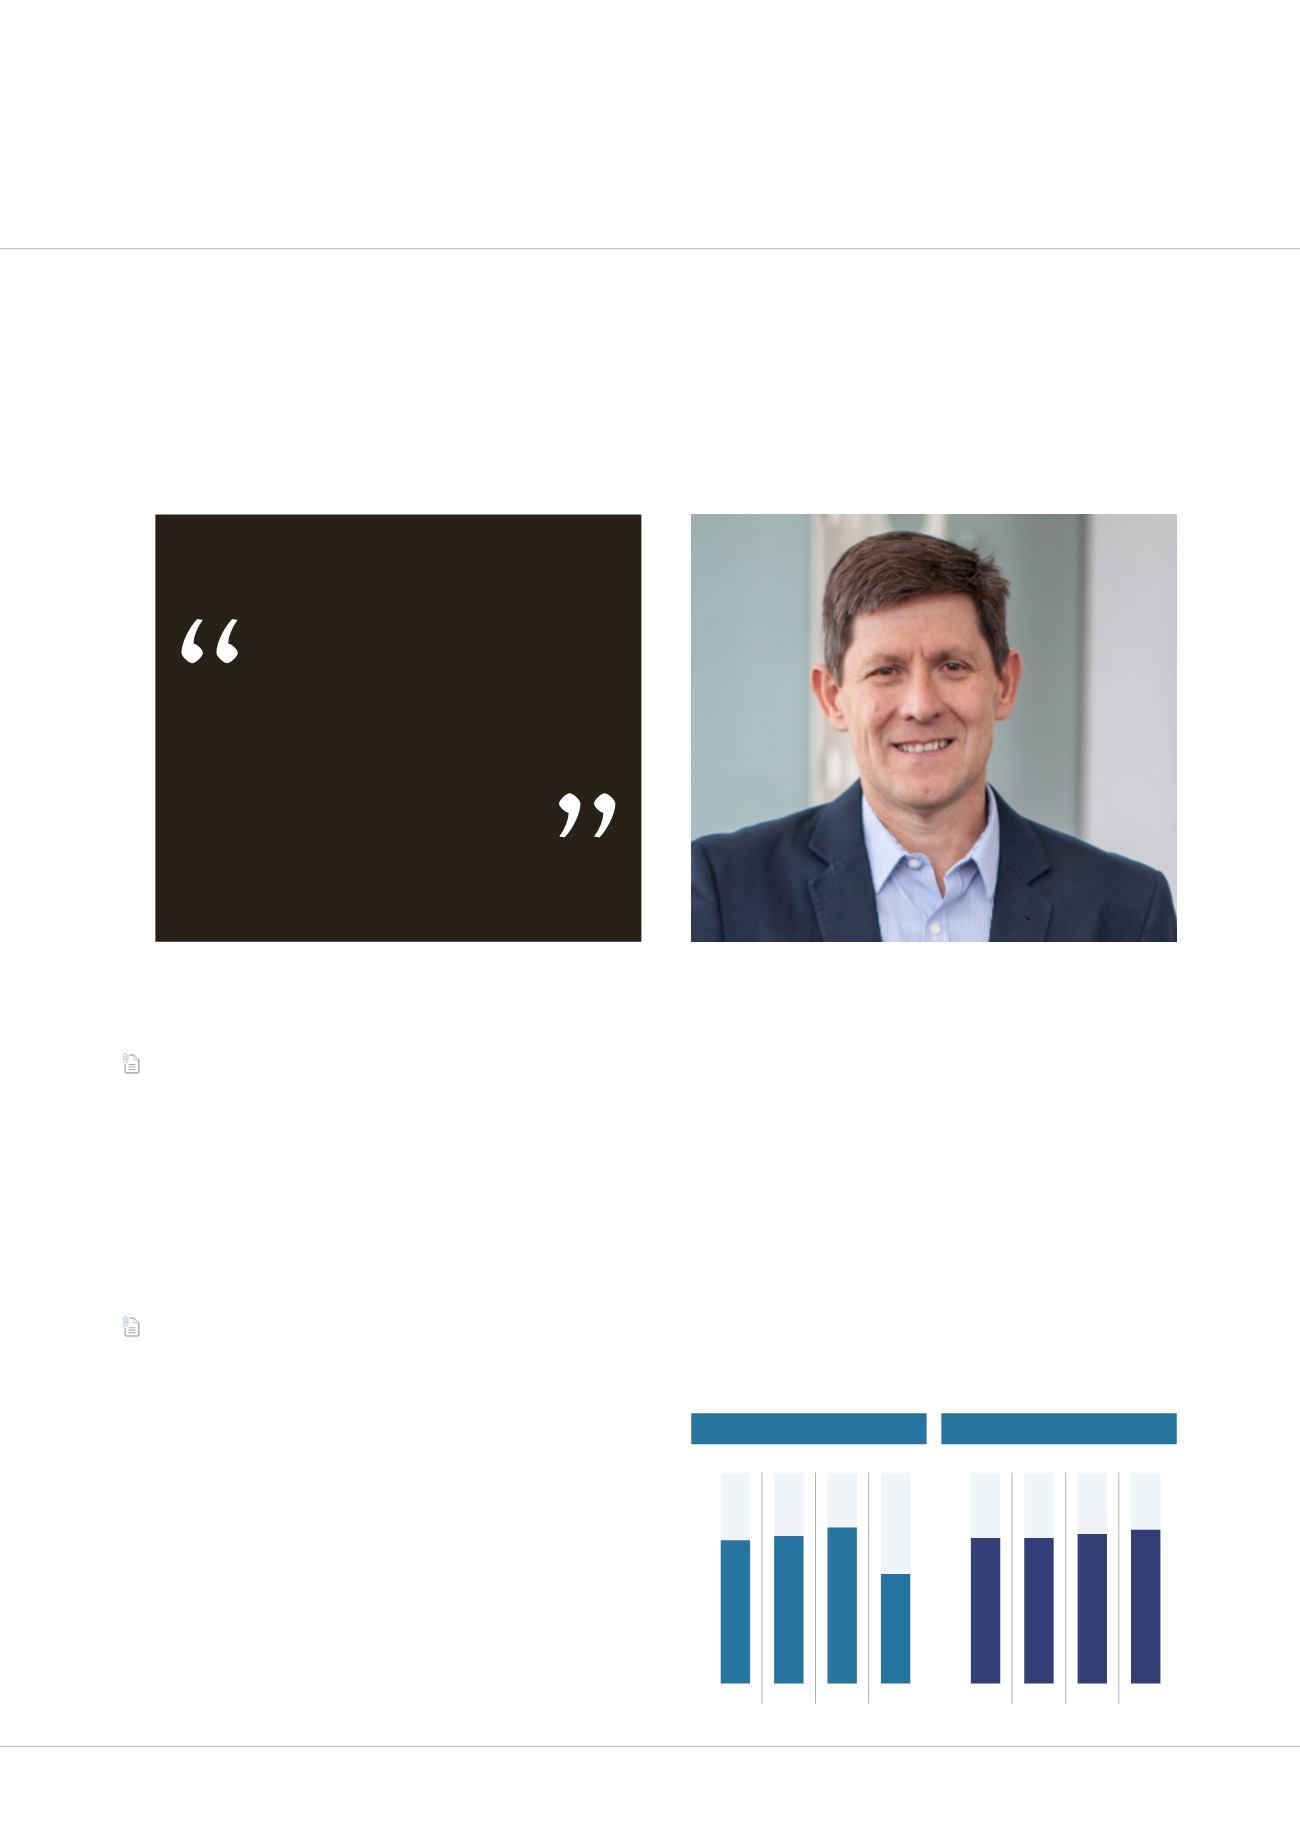
Trading overview
0
2
4
6
8
10
5,2%
7,4%
7,0%
6,8%
Jun
2013
Jun
2014
Jun
2015
Jun
2016
0
2
4
6
8
10
7,3%
7,1%
6,9%
6,9%
Jun
2013
Jun
2014
Jun
2015
Jun
2016
Trading density growth
Rent ratio
(rental as % of turnover)
Pieter Prinsloo,
chief executive officer
As the listed property sector expands and competition intensifies, a
disciplined strategy becomes increasingly important. While Hyprop’s
strategy is detailed on page 5, I reiterate that key for our group is
our focus on the type and quality of assets. In terms of type, we
only consider ownership in large shopping malls. In terms of quality,
we consider the location, dominance and quality of the mall itself.
We focus on those with a strong consumer base and very strong
tenant mix, and ensure they are well situated in key cities or strong
metropolitan areas.
Against this background, a highlight of the year was our expansion
into South-Eastern Europe after acquiring a 60% share in two Delta
City malls in Montenegro and Serbia. Funded with EUR denominated
loans, these acquisitions (detailed on page 54) are an attractive
investment as they complement our strategy to acquire or develop
high-quality, income-producing shopping centres in emerging markets.
The financial director’s report details corporate activity post year-end.
In summary, we raised R700 million in new equity and issued new
corporate bonds of R1,2 billion, used to repay bank debt, while non-
core disposals strengthened our balance sheet by R365 million.
Over the past four years, we have made solid progress in
geographically diversifying our portfolio, which spreads the risk of
low economic growth in a particular region. At year-end, South Africa
was still the source of over 80% of our distributable income. We do,
however, expect to benefit further from our investments in South-
Eastern Europe and sub-Saharan Africa which will be included for the
full year.
Over the past four years, we
have made solid progress in
geographically diversifying
our portfolio, which spreads
the risk of low economic
growth in a particular region.