


 116 / 160

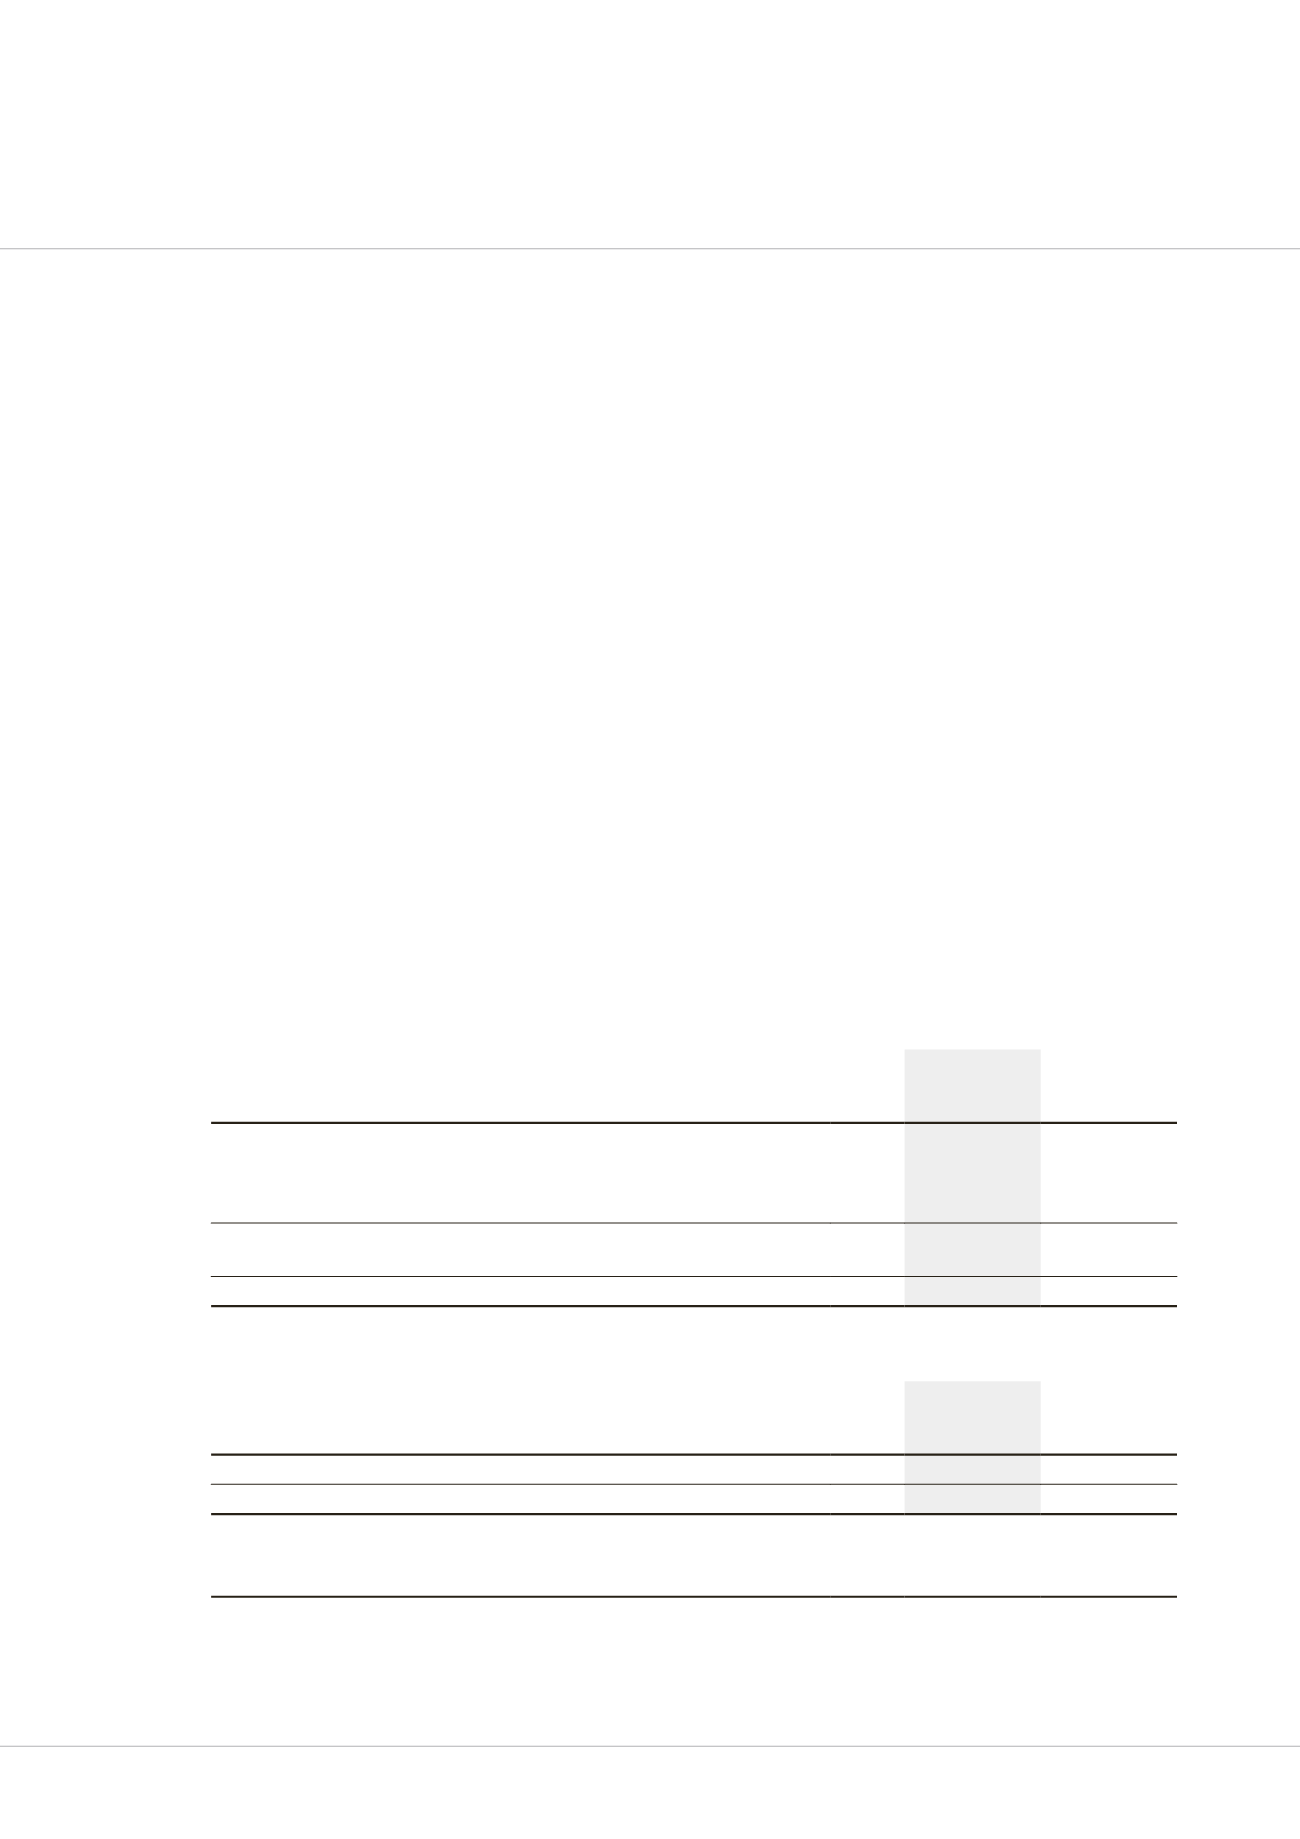
NOTES TO THE FINANCIAL STATEMENTS
continued
for the year ended 30 June 2016
Hyprop Investments Limited
Group annual financial statements 2016
114
2.
Investment property
continued
2.5 Investment property valuation
continued
Valuation techniques underlying management’s estimation of fair value
The valuations were determined using discounted cash flow projections. These inputs include:
Future rental cash flows:
Based on the location, type and quality of the properties and supported by the terms of any existing leases or
other contracts or external evidence such as current market rentals for similar properties.
Discount rates:
The discount rate is the rate of return used in a discounted cash flow analysis to determine the present value of future cash
flows, and take into account an assessment of the uncertainty in the amount and timing of future cash flows.
Vacancy rates:
Based on current and expected future market conditions after expiry of any current leases, as well as tenant failures during
the course of a lease.
Maintenance costs:
Including necessary investments to maintain functionality of the property for its expected useful life.
Capitalisation rates:
Based on location, size and quality of the properties and taking into account market data at the valuation date.
Terminal value:
Taking into account assumptions regarding maintenance costs, vacancy rates and market rentals.
The valuation methods applied by the independent valuers were the same as the prior year.
Fair value hierarchy
Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants
at the measurement date, regardless of whether that price is directly observable or estimated using another valuation technique. In estimating
the fair value of an asset or a liability, the group takes into account the characteristics of the asset or liability if market participants would take
those characteristics into account when pricing the asset or liability at the measurement date.
In addition, for financial reporting purposes, fair value measurements are categorised into level 1, 2 or 3 based on the degree to which the
inputs to the fair value measurements are observable. The three levels are explained as follows:
Level 1
– inputs are quoted prices in active markets for identical assets or liabilities that the company can access at the measurement date.
These quoted prices are unadjusted.
Level 2
– these are inputs, other than quoted prices included in level 1, that are observable for the asset or liability, either directly or
indirectly.
Level 3
– inputs are unobservable inputs for the asset or liability.
Recurring fair value
measurements – level 3
June 2016
Valuation
R000
June 2015
Valuation
R000
South Africa
(1)
Shopping centres
25 282 472
23 408 630
Value centres
1 109 000
1 112 000
Standalone offices
108 300
480 000
Sub-Saharan Africa (excluding South Africa)
Ikeja City Mall (Lagos, Nigeria)
2 322 426
Total group
28 822 198
25 000 630
(1)
Excludes property held-for-sale
Non-recurring fair value
measurements – level 3
June 2016
Valuation
R000
June 2015
Valuation
R000
Assets held-for-sale
1 230 775
1 225 775
Total group
1 230 775
1 225 775
There are inter-relationships between unobservable inputs. Expected vacancy rates may impact the yield, with higher vacancy rates resulting
in higher yields. An increase in future rental income may be linked with higher costs. If the remaining lease term increases, the yield may
decrease.